
Why We Started Numza
A casual lunch conversation in Japan revealed an uncomfortable truth about hidden spending habits, inspiring the creation of Numza.
One afternoon over lunch in Tokyo, a casual conversation with a colleague took an unexpected turn.
We were talking about the rising cost of living in Japan. Grocery prices had climbed, utility bills kept ticking upward, and our salaries weren’t keeping pace.
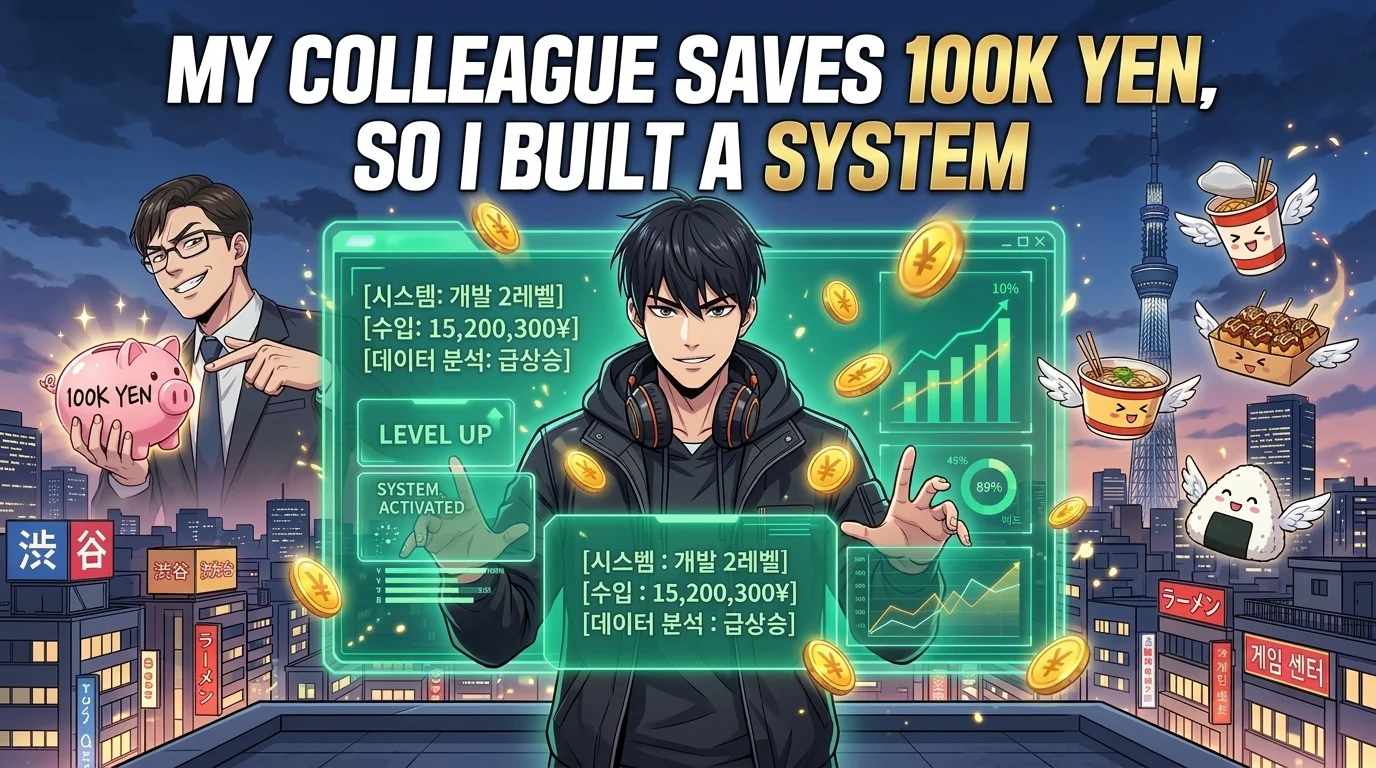
Then my colleague mentioned something in passing: even after dining out a couple of times a week, he still managed to save roughly ¥100,000 every month.
I looked at him in disbelief. Save ¥100,000 a month? I was living payday to payday, watching my bank balance hover near zero before every direct deposit.
Then came the question that stopped me cold:
“Wait, don’t you earn more than I do? Where is all your money going?”
The Belief vs. The Reality
I sat there with no answer.
What I believed: I was being frugal. I cooked at home nearly every evening, avoided expensive nights out, and treated myself to a modest takeaway dinner perhaps once a week.
What the numbers actually showed: I wasn’t saving anything. I genuinely had no idea where the money went.
That evening, determined to find out, I downloaded several personal finance apps. But almost immediately, I hit a wall. Most expense trackers made recording an expense feel like another chore. Too many required fields, too many taps, and rigid category trees that felt like doing data entry for an accounting firm. Within a few days, I stopped opening them. I wanted something I would actually use every single day.
I realized something important about my own situation.
I didn’t need another app lecturing me to stop buying coffee.
I didn’t need a complicated fifty-page financial plan.
I just needed visibility.
And that became the idea behind Numza.
Building What We Needed
I called a close friend with a background in finance. We spent hours talking about why tracking personal expenses always felt so exhausting, and we decided to build our own solution.
We kept the team small and focused. I built the first version of Numza myself, while my co-founder focused on the analytical side of the product.
That experience shaped how we wanted Numza to feel. Tracking your spending shouldn’t feel like punishment or accounting homework. It should be simple enough that you actually keep doing it.
That’s why we wanted recording an expense to take seconds, whether you type it, speak it, or scan a receipt. And once your expenses are recorded, Numza should help you understand your spending habits without making you feel guilty about them.
What Daily Use Revealed
We started using Numza ourselves for every transaction, while sharing early builds with friends.
Living with the app quickly shattered my own assumptions.
Those “occasional” takeaway dinners were happening far more often than I thought. What felt like a few small purchases each week had quietly become tens of thousands of yen a month. My digital subscriptions were even more eye-opening. I found multiple premium services I barely touched, subscriptions that could easily be dropped to free, ad-supported tiers or canceled altogether without affecting my life at all.
I didn’t need extreme austerity. I just needed visibility.
Why We Built Numza
We don’t want Numza to tell you what you should or shouldn’t spend.
We want to make it easier to see where your money is actually going.
Because once you can see it clearly, you can decide for yourself what matters to you.
That’s the kind of expense tracker we wanted for ourselves. And that’s why we built Numza.